Last updated October 30, 2026
 Home additions & ADU
 Kitchen remodeling
 Bathroom remodeling
 Roofing
 Windows & doors
 Driveway & pavers
 Fence
Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Construction Emergency Preparedness Guide for Indio Homes
When a monsoon cell drops an inch of rain in 45 minutes on an Indio home with a single ponding roof drain, the water doesn’t wait for a roofing contractor to be available. The decisions made in the first two hours determine whether you’re repairing a leak or gutting drywall. Most Indio homeowners are borrowing their emergency plans from flood-zone or cold-climate templates, and those templates fail here. This guide covers the desert-specific failure events that actually hit Indio homes: monsoon water intrusion, heat-driven structural stress, and wind events that expose weaknesses in stucco and roofing assemblies. For more guides & resources on protecting your home, see our blog. You’ll learn the exact response sequences, documentation protocols, and contractor vetting steps that protect both your home and your insurance claim.
Quick Answer
Construction emergencies in Indio cluster around three desert-specific events: monsoon-driven water intrusion, summer HVAC failure with structural heat consequences, and wind damage to stucco and roofing. The right response is a documented sequence: contain the immediate damage, document everything with photos before touching anything, shut off water or power only when safe, and call a licensed General Contractor in Indio who can assess the full scope before you file an insurance claim. Most homeowners lose claim value because they clean up too fast and document too late.
Styles & brands we work with
Table of Contents
- Monsoon Intrusion: The First Two Hours
- Summer Heat Emergencies in Unoccupied Homes
- Post-Wind-Event Assessment: Stucco, Roofing, and Patio Structures
- Tarping and Containing: What to Do Before Help Arrives
- Documentation Protocol for Insurance Claims
- Emergency Contractor Vetting Under Pressure
- Pre-Season Preparation: What to Do Before the Next Event
- Common Mistakes to Avoid
Monsoon Intrusion: The First Two Hours
Monsoon rain in Indio is not like rain in Seattle or Portland. It arrives as a wall of water, often with wind driving it sideways against walls and windows that were never designed to see that kind of lateral moisture load. Homes built for dry conditions have roof drains, scuppers, and flashing details that work fine in a light sprinkle and fail catastrophically when an inch falls in under an hour. When water starts coming in, the sequence of your response matters more than the speed of it.
What to Do First
- Photograph the active intrusion before touching anything. Use your phone. Capture the water path, the ceiling stain, the bubbling paint, the wet carpet. These photos establish causation for your insurer. Adjusters routinely deny claims where homeowners cleaned up before documenting.
- Contain the water at the lowest point. If water is coming through a ceiling, place buckets or bins under the drip. If it’s running down a wall, move furniture and electronics away. If you have plastic sheeting or a tarp, lay it over floors where water is pooling.
- Do not puncture the ceiling. This is the single most common homeowner mistake we see after monsoon events in Indio. Water pooling above drywall creates a heavy, unstable reservoir. Poking a hole releases the water but also destroys the drywall and often drops a slurry of insulation and debris into your living space. Let it drain naturally through existing openings, or wait for a professional with water extraction equipment.
- Kill power to affected circuits at the breaker. Only if the panel is dry and you can reach it safely. Water and electricity don’t mix, and a wet ceiling above a light fixture is a shock hazard. If you have any doubt, shut off the main breaker.
- Move valuables and document the room. Take wide-angle photos of every affected space before moving furniture. Your claim depends on proving what was there and what got wet.
What to Tarp, What Not to Disturb
The instinct to get on the roof during a storm is dangerous and usually counterproductive. Wait for the rain to stop. Once it does, a tarp over the suspected entry point is the right move, but only if you can do it safely from a ladder. Never walk on a wet tile roof or a membrane roof that’s ponding water. If the intrusion is coming through a window or door, check the weep holes and weatherstripping first. We’ve seen Indio homes where water “leaks” through sliding doors were really just clogged weep holes backing up under wind-driven rain. A wire hanger and five minutes solves that. If the water is coming through the wall itself, that’s a stucco or flashing failure, and it needs a professional assessment before you make it worse. See our Construction Warning Signs: A Indio Homeowner’s Reference Guide for what to watch for.
Summer Heat Emergencies in Unoccupied Homes
Indio regularly sees summer stretches above 110°F. When a home’s HVAC system fails while the owners are away for a week or two, the consequences go far beyond comfort. Interior temperatures in an unventilated Indio home can exceed 130°F in a single afternoon. That kind of heat does structural and mechanical damage that most homeowners never anticipate.
What Heat Does to a Home
- PEX plumbing degrades. PEX is rated for continuous service at 180°F at pressure, but sustained attic temperatures combined with water sitting stagnant in lines pushes the material toward its limits. Fittings fail first. We’ve opened walls in Indio homes after heat events and found PEX fittings that had softened and deformed, creating slow leaks that ran for weeks before anyone noticed.
- HVAC refrigerant systems overwork and burn out. When the cooling system fails, the compressor is often the first casualty. But the secondary failure is the real problem: refrigerant lines running through attics that hit 150°F cause pressure spikes that can crack linesets or blow seals. A system that failed for one reason can be destroyed by the heat if it tries to restart automatically.
- Interior finishes delaminate. Cabinet doors warp. Countertop seams open. LVP flooring expands and buckles. Drywall tape peels. None of this is covered by standard homeowners insurance unless the heat event was caused by a covered peril, which is why documentation of the HVAC failure itself matters.
- Adhesives and sealants break down. Shower surrounds, backsplashes, and window seals all rely on adhesives that have specific temperature tolerances. Sustained extreme heat accelerates their failure curve by years in a matter of days.
Protocol for Unoccupied Homes
- Install a WiFi thermostat with high-temp alerts. Ecobee and Nest both offer alerts when interior temperatures exceed a set threshold. This is the single most effective pre-season preparation for Indio homeowners who travel in summer.
- Set the AC no higher than 85°F when away. The temptation to save money by setting it to 90 or turning it off entirely is false economy. The repair costs from heat damage dwarf the energy savings.
- Have a neighbor or relative do a visual walk-through every 48-72 hours. They should check for water stains, warped doors, and the sound of the AC running. If they hear nothing on a 110°F day, that’s an emergency.
- If cooling fails while away, get someone in fast. Window AC units in key rooms can hold temperatures down temporarily while you arrange repairs. Even one 8,000 BTU unit in a closed-off bedroom can protect that room’s contents. The rest of the house will still cook, but you’ll buy time for the HVAC contractor.
Home Remodeling in Indio projects often reveal heat damage that predated the remodel. We’ve seen kitchens where cabinet warping was initially diagnosed as a hinge problem, but the real culprit was three weeks of 130°F interior heat the summer before.
Post-Wind-Event Assessment: Stucco, Roofing, and Patio Structures
Desert winds in Indio are routine, but the gust events that accompany monsoons or Santa Ana patterns are different. They’re strong enough to lift roof edges, drive debris into walls, and stress stucco beyond its design limits. After a wind event, walk your property with a specific checklist. Not a general look-around. A checklist.
Stucco Delamination: What It Looks Like and Why It Matters
Stucco fails when the bond between the stucco layer and the underlying substrate breaks down. Wind-driven rain accelerates this by forcing moisture behind the stucco at any crack or penetration. After a wind event, look for: hairline cracks that weren’t there before, especially around windows and door frames; areas where the stucco sounds hollow when tapped; staining or efflorescence (white mineral deposits) on the stucco surface. If you find any of these, don’t ignore them. Delaminated stucco lets water in during the next rain event, and the repair goes from a patch job to a full re-stucco in a matter of months. Indio homes with older three-coat stucco systems are especially vulnerable because the paper-backed lath degrades over time in our heat.
Roofing Uplift: What’s Safe to Check
You don’t need to get on the roof to assess uplift damage. Stand at the street and look at the roof line. Look for: shingles or tiles that are lifted, curled, or missing; exposed underlayment; flashing that’s pulled away from penetrations like vents and chimneys; any debris that’s sitting on the roof surface. If you have a tile roof, look for broken or displaced tiles, especially at hips and ridges where wind pressure concentrates. If you have a membrane roof, look for bubbles or wrinkles that indicate the membrane has separated from the deck. These are all reportable conditions. Call a contractor with roofing expertise, and send them the photos before they come out. That way they arrive with the right materials on the truck.
Patio Structures and Pergolas
Free-standing patio structures, pergolas, and shade sails take the brunt of wind events. Inspect the anchor points: are posts still plumb? Are the anchor bolts tight? Has the structure shifted on its footings? Check the connections between the top plate and the posts. Check any hardware for rust or bending. A pergola that’s leaning 2 degrees after a wind event is a teardown waiting to happen. We recommend homeowners inspect patio structures after every major wind event in Indio, not just after monsoons. The cumulative effect of repeated wind loading is what eventually fails these structures.
Tarping and Containing: What to Do Before Help Arrives
Emergency tarping is a stopgap measure, not a repair. Its purpose is to keep further water out until a permanent fix can be installed. Done wrong, it causes more damage than it prevents. Done right, it saves your ceilings, your floors, and your claim.
The Right Way to Tarp a Roof Leak
- Wait for the rain to stop completely. A wet roof is slippery. A wet tile roof is treacherous. No emergency is made better by a fall from a ladder.
- Use a tarp that extends at least 4 feet past the suspected leak in every direction. Water travels. The entry point is rarely directly above the ceiling stain. On a sloped roof, water runs down the underlayment before finding a hole. Tarp generously.
- Secure the tarp with 1×2 wood strips, not rocks or bricks. Rocks shift. Bricks slide. Wood strips screwed through the tarp and into the roof deck create a mechanical connection that holds in wind. If you can’t screw into the deck, use sandbags placed at the tarp’s edges on a flat roof.
- Run the tarp over the ridge if the leak is near the ridge. Tucking it under the ridge solves nothing. The water just runs under the tarp and into the same hole. Wrap it over the top and secure it on both sides.
- Never nail or screw through the membrane of a flat roof. If your Indio home has a flat or low-slope membrane roof, call a professional for tarping. Puncturing the membrane creates a new leak and voids most roofing warranties.
Interior Containment
While the roof is being addressed, contain the interior. Move furniture out of the affected area. Lay plastic sheeting over floors. If carpet is soaked, it needs to come up. Wet carpet pad in an Indio summer becomes a mold factory within 48 hours. If you can, cut out the wet pad yourself and leave the carpet. If you can’t, call a water extraction company. Don’t wait for the insurance adjuster to tell you to do this. You have a duty to mitigate damages. Document before you cut, then cut.
Documentation Protocol for Insurance Claims
Insurance claims on construction damage are won or lost on documentation. Not on the quality of the repair. Not on the contractor you choose. On what you can prove, when you can prove it, and how clearly the causation chain is established. Here’s the protocol we recommend to every Indio homeowner who calls us after an event.
The Photo Sequence
- Wide shots first. Stand in the doorway and photograph the entire room before you move anything. These establish the baseline.
- Medium shots second. Photograph each damaged area from enough distance to show context. The ceiling stain with the light fixture in frame. The wet carpet with the wall in frame.
- Close-ups third. Get detail on the water path, the bubbling paint, the warped cabinet door, the stucco crack. Use flash if the light is poor. These photos show the damage mechanism.
- Exterior shots of the suspected entry point. The roof area, the window, the stucco wall. If you can safely photograph the roof from a ladder or the ground with a zoom lens, do it.
- Photo everything before you touch anything. Once you move furniture or start cleanup, the scene is altered and the adjuster can argue contributory damage.
The Timeline Document
Write down, in a simple note on your phone, the sequence of events. When you first noticed the damage. When the rain started and stopped. When you called your insurance company. When you called a contractor. When you started mitigation. Every entry with a date and time. This timeline is admissible evidence and it establishes that you acted reasonably and quickly. Adjusters look for homeowner negligence, and a clear timeline defeats that argument before it starts.
Why a General Contractor Walk Before the Adjuster Visit Matters
Insurance adjusters are generalists. They’re evaluating your claim based on what you tell them and what they can see. A general contractor’s walk-through produces a documented list of every affected system: structural, electrical, plumbing, finishes. That list becomes the scope of work that the adjuster uses to calculate your payout. If the walk happens after the adjuster’s visit, any missed items are gone. The adjuster already closed the claim. We’ve seen Indio homeowners leave $15,000 on the table because the adjuster didn’t notice a heat-stressed refrigerant line or a moisture-damaged electrical panel, and the contractor wasn’t there to point it out. Read our DIY vs Professional Construction: The Indio Homeowner’s Decision Guide to understand when to call in the pros. Get the contractor walk first. Then the adjuster. The order matters.
Emergency Contractor Vetting Under Pressure
After a monsoon or wind event in Indio, the storm chasers arrive. They’re door-knockers with out-of-state plates, pressure tactics, and quoted prices that are either suspiciously low or alarmingly high. They concentrate in the Coachella Valley after weather events because they know homeowners are scared and cash-rich from insurance payouts. Here are the three questions to ask before letting anyone on your roof.
Question 1: “Show me your California contractor’s license and your workers’ compensation certificate.”
In California, any contractor performing work on your home must be licensed by the Contractors State License Board. Ask for the license number and verify it on the CSLB website before they start. Ask for workers’ comp. If a worker falls off your roof and the contractor doesn’t carry comp, that worker’s medical bills become your problem. Your homeowners insurance will fight it, but you’ll spend a year in the process. A legitimate contractor in Indio hands over both documents without hesitation. A storm chaser suddenly remembers he left his license in the truck and never comes back.
Question 2: “Who is doing the actual work, your crew or subcontractors?”
Storm response work is often subcontracted out to whoever is available that week. That means the person who quoted you the job is not the person who will be on your roof. Ask for the names of the subs, ask if they’re licensed, and ask who carries the liability if the sub damages your roof further. If the answer is vague, the risk is yours. A full-scope general contractor like Briar handles the work from Briar Contractors home base with accountability for every trade. We have partner access to roofing materials from GAF, CertainTeed, Owens Corning, and Boral, and we coordinate the repair under one contract instead of farming out responsibility.
Question 3: “Can you put the scope of work and price in writing before you start?”
Verbal quotes are worthless after a storm. A legitimate contractor writes a scope of work, a materials list, and a fixed price. Storm chasers quote a number, take a deposit, and “discover” additional damage once the roof is open. The price triples. If they won’t put it in writing, send them away. If they want a deposit larger than 10% or $1,000, whichever is less (the California legal limit), send them away.
After you’ve vetted your contractor, ask about materials. A repair that uses substandard materials fails again in the next monsoon. We spec roofing repairs with reputable brands, not whatever is cheapest at the local yard. The material matters as much as the installation.
Pre-Season Preparation: What to Do Before the Next Event
The best emergency response is the one you never have to use. Indio homeowners who prepare before monsoon season and before summer heat waves are the ones whose claims are smaller, whose repairs are faster, and whose stress levels stay manageable. Here’s the pre-season checklist we recommend.
Monsoon Season Prep (May-June)
- Clean all roof drains, scuppers, and gutters. Indio’s dry months deposit dust, leaves, and debris that harden into a clog. A single clogged drain turns a light rain into a ponding failure. Do this in May, before the first monsoon cell.
- Inspect and re-seal windows and doors. Check the weep holes. Check the weatherstripping. Check the caulking around frames. Re-seal any gaps. Wind-driven rain finds every gap.
- Photograph your roof condition. Take photos of your roof, your stucco, and your windows before the season. If damage happens, you have a baseline to compare against. This is the single most valuable pre-season documentation you can create.
- Review your insurance policy. Know your deductible. Know what’s covered and what’s excluded. Know the claim filing deadline. Call your agent and ask about flood insurance. Standard homeowners policies do not cover flood damage, and Indio monsoon events occasionally trigger the exclusion.
Summer Heat Season Prep (May-September)
- Have your HVAC system serviced in April or May. Change filters, check refrigerant levels, clean coils. A system that’s already stressed is more likely to fail during a heat wave.
- Install high-temp alerts. If you travel, a WiFi thermostat with alerts is the cheapest insurance you’ll ever buy.
- Inspect your attic ventilation. In Indio, attic temperatures routinely exceed 150°F in summer. Proper ventilation slows heat damage to everything: roofing underlayment, PEX, wiring, insulation. Make sure vents are not blocked.
- Check your window seals and door seals for heat leaks. Heat intrusion accelerates every other failure mode. Sealed windows and doors keep interior temperatures manageable when the AC is running normally.
Common Mistakes to Avoid
- Puncturing the ceiling to drain pooled water. We mentioned this earlier, and it bears repeating. The water you release destroys the drywall and drops a mess into your living space. Let it drain naturally, or wait for professionals with extraction equipment.
- Cleaning up before photographing. Once the scene is altered, the insurance adjuster can claim the damage was pre-existing or not as severe as reported. Photograph first. Always photograph first.
- Calling the insurance company before calling a contractor. The adjuster will ask what’s damaged. If you haven’t had a professional assessment, you’ll underreport. Get the contractor walk first, then file the claim with a complete list.
- Hiring the first contractor who knocks on your door. After Indio weather events, unlicensed storm chasers work the neighborhoods. They’ll pressure you into a fast decision with a deposit. The deposit disappears, and so do they.
- Ignoring small stucco cracks after a wind event. That hairline crack is the entry point for the next monsoon. A $500 patch today prevents a $15,000 re-stucco in two years.
- Turning off the AC completely when leaving for summer travel. The energy savings are meaningless compared to the repair costs from heat damage. Set it at 85°F and let it run.
- Assuming flood damage is covered. It’s not, unless you have a separate flood policy. Read your policy before the rain falls.
See the difference
 Before
 After
 Before
 After
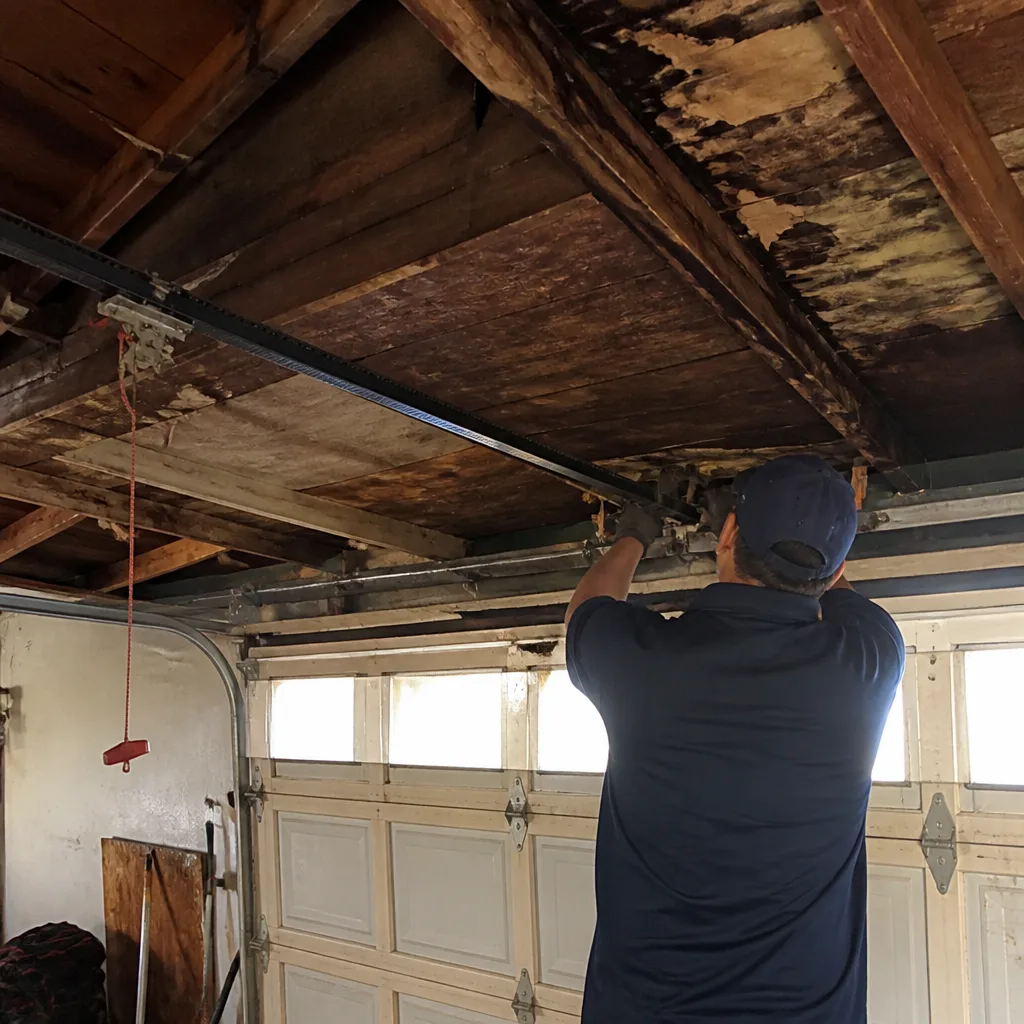 Before
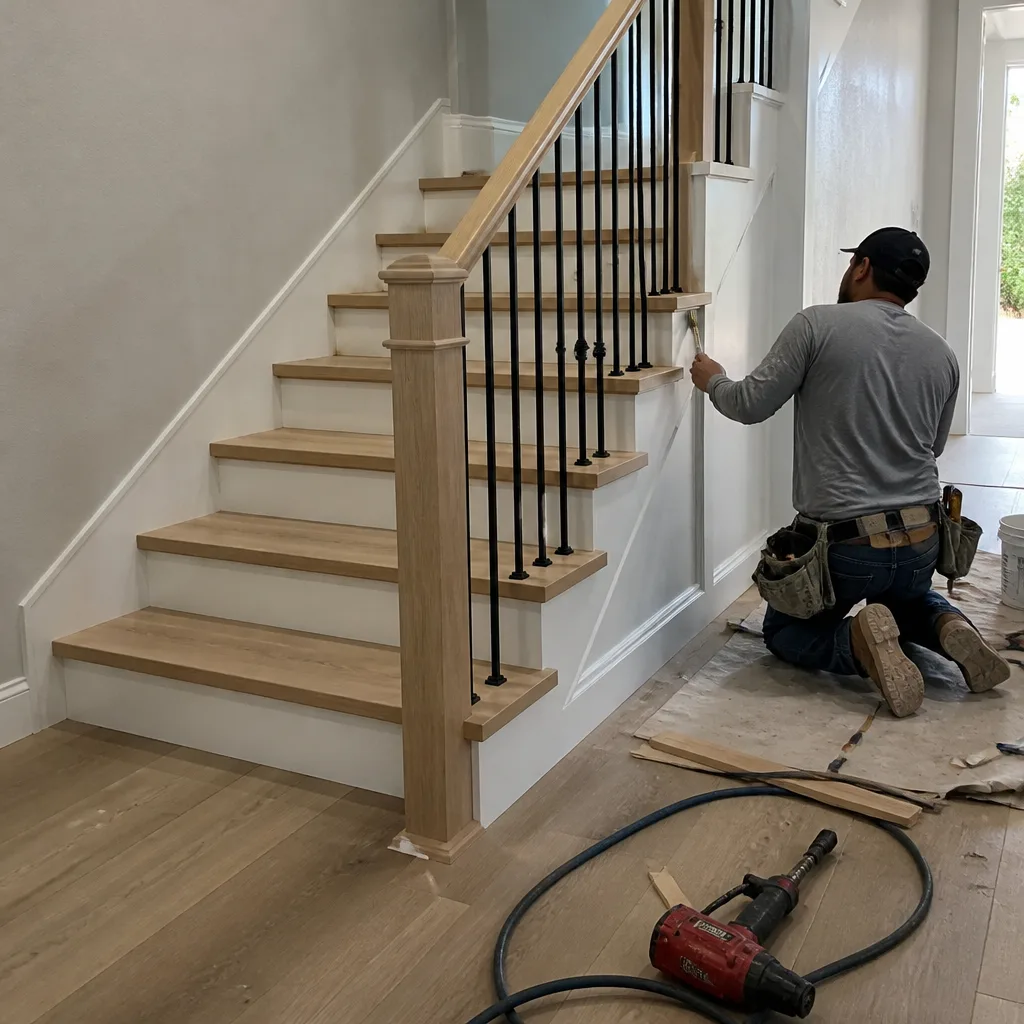 After
When to Call a Professional
Call a professional when the damage involves any structural system: roofing, stucco, foundation, load-bearing walls. Call when water intrusion has affected more than a single room. Call when the electrical panel has been exposed to water or heat stress. Call when you see signs of stucco delamination, roofing uplift, or any movement in the building frame. Call when the HVAC system failed during a heat event and the home has been unoccupied. We’ve walked properties in Indio where the homeowner thought they had a minor leak and actually had a roof deck that was 40% compromised. The sooner a professional assesses the scope, the smaller the repair. Home Renovation in Indio projects often begin as emergency responses that revealed deeper problems. Briar Contractors offers free estimates in Indio – call (833) 467-4442.
Frequently Asked Questions
Emergency roof tarping in Indio typically ranges from $250 to $600 depending on roof size and accessibility. Permanent repairs after monsoon or wind damage usually run $800 to $3,500 for localized damage, while full roof replacements from storm damage can cost $12,000 to $35,000 depending on materials and roof complexity. Your deductible is often the larger cost, which is why a complete contractor assessment before filing matters. Call (833) 467-4442 for an exact quote on your specific damage.
Standard homeowners insurance covers wind and rain damage that enters through a storm-created opening in the roof or walls. It does not cover flood damage from rising water, and it does not cover damage from water that entered through pre-existing holes or maintenance failures. The distinction between “storm-created opening” and “maintenance failure” is where most Indio claims get denied. This is why the pre-season photo documentation matters so much. If your claim is denied for maintenance failure, call us at (833) 467-4442 – we can help you scope the repair regardless.
Localized roof or stucco repairs in Indio typically take 2 to 5 days once materials are on site. Full roof replacements take 1 to 2 weeks. Water extraction and interior drywall repair add another 1 to 2 weeks. During monsoon season, contractor availability stretches these timelines, which is why pre-season preparation and early response matter. Call (833) 467-4442 to get on our schedule before the next event.
In most cases, no. If your repair cost is under or close to your deductible, filing a claim adds a claim record to your policy with no payout. That record can increase your premium or trigger non-renewal. Get a contractor estimate first. If the repair is under $2,000-$3,000 and your deductible is $2,500, paying out of pocket is usually the right call. We help Indio homeowners run this math every year. Call (833) 467-4442 for an honest assessment.
Call or text a neighbor or relative and ask them to check the house. If the interior temperature is climbing toward 90°F, have them place window AC units in key rooms to hold temperatures down. Call an HVAC contractor immediately. If the interior has already exceeded 100°F for more than 48 hours, you may also have heat damage to PEX plumbing, cabinetry, and flooring that will need assessment. Have someone document the interior temperature with photos of a thermometer if possible. That documentation supports any subsequent claim.
Emergency repairs to stop active water intrusion or secure the home are generally exempt from the permit requirement at the time of the emergency. However, permanent repairs that involve structural, electrical, or plumbing work do require permits from the City of Indio. A licensed general contractor handles the permit process as part of the scope of work. We pull permits for every job where they’re required and close them out with final inspections. Call (833) 467-4442 with questions about your specific situation.
The Bottom Line
Construction emergencies in Indio are not like emergencies anywhere else. The desert climate creates failure modes that other emergency guides don’t address: monsoon water intrusion into structures designed for dry heat, summer HVAC failures that turn an unoccupied home into an oven, and wind events that expose stucco and roofing weaknesses over time. The homeowners who fare best are the ones who prepared in May, documented their property’s condition before the season, responded in the first two hours with the right sequence, and called a licensed professional before cleanup or insurance claims. The homeowners who fare worst are the ones who punched holes in their ceilings, waited to photograph the damage, and hired the first storm chaser who knocked. Preparation is cheap. Recovery is not.
Written by the team at Briar Contractors, serving Indio since 2018.